The short answer
A lifestyle spending account (LSA) is money your employer puts aside for you to spend on wellness and everyday life, like fitness, mental health, and healthy food. Your employer funds it and decides what counts. Unlike an HSA or FSA, it is not pre-tax, so the money you use is usually taxed as income.
If your offer letter or benefits page mentions an LSA, you are not alone in wondering what it is. It is one of the newer perks out there, and every company sets it up a little differently.
Here is the plain version.
How an LSA works
Your employer picks an amount, say a set number of dollars a month or a year. You spend it on things the company allows, then submit a receipt to get paid back. Some companies use a card instead, so you pay straight from the account.
A few things are true of most LSAs:
- Your employer pays for it. You do not put any of your own salary in.
- Your employer writes the rules. They decide what counts, how much you get, and when it resets.
- It is flexible. It usually covers a wider range of things than a classic health benefit.
- It is taxed. The money you get is usually treated as income.
LSA vs. HSA vs. FSA
These three get mixed up all the time. The big differences are who pays in, how taxes work, and what you can spend on.
| Question | LSA | HSA | FSA |
|---|---|---|---|
| Who puts money in? | Your employer | You, and sometimes your employer | You, and sometimes your employer |
| Taxes | Post-tax, taxed as income | Pre-tax | Pre-tax |
| What it covers | Whatever your employer allows | Medical expenses | Medical expenses |
| Healthy snacks? | Often, if your plan allows food | Generally no | Generally no |
That last row is the one people ask about most. HSAs and FSAs are for medical costs, like copays, prescriptions, and some supplies. Snacks, even very healthy ones, are generally not eligible. An LSA is different, because your employer decides what goes on the list.
What LSAs usually cover
Because every plan is custom, there is no single list. But these show up a lot:
- Gym memberships, fitness classes, and workout gear
- Meditation, sleep, and therapy apps
- Healthy food, snacks, and meal kits
- Home office gear, like a chair or a desk
- Learning, like a cooking class or a language app
- Sometimes travel, pet care, or child care
If you want more ideas, we made a longer list in what can you buy with a wellness stipend.
The tax part, in plain English
Since an LSA is post-tax, the money you spend is usually added to your taxable income. So if you use the full amount, a part of it goes to taxes. You still come out ahead, because it is money you would not have had at all.
We are not tax experts, and your situation may be different. If you want the details, ask your HR team or a tax professional.
Good to know: LSA money often resets on a schedule, and many plans do not roll it over. Look up your deadline so you do not leave money on the table.
How to use your LSA on something you will enjoy
The best LSA buys are things you use often. A gym membership you skip is not much of a perk. A snack you reach for at 3 p.m. every day is.
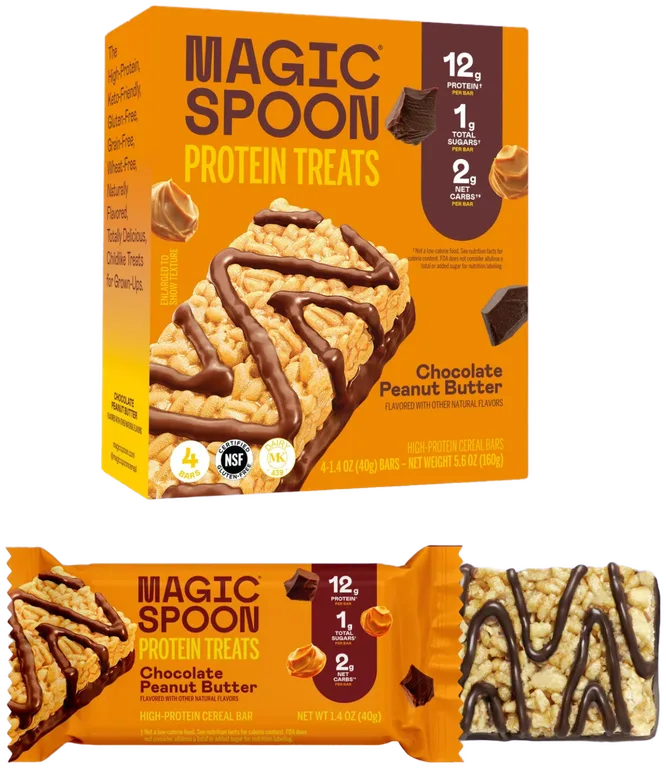
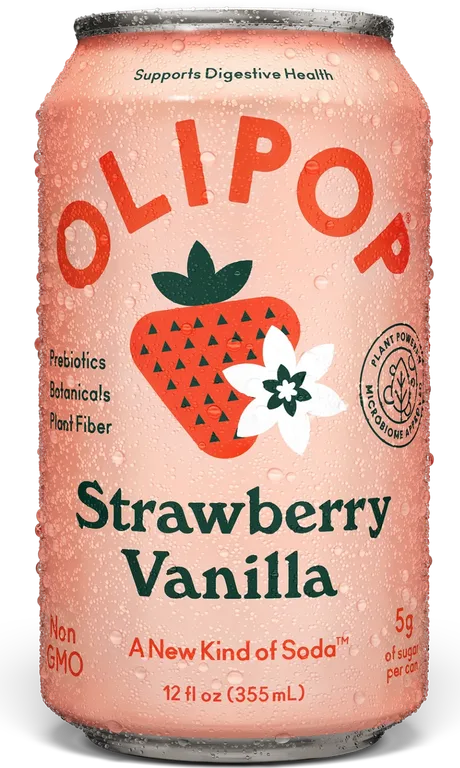
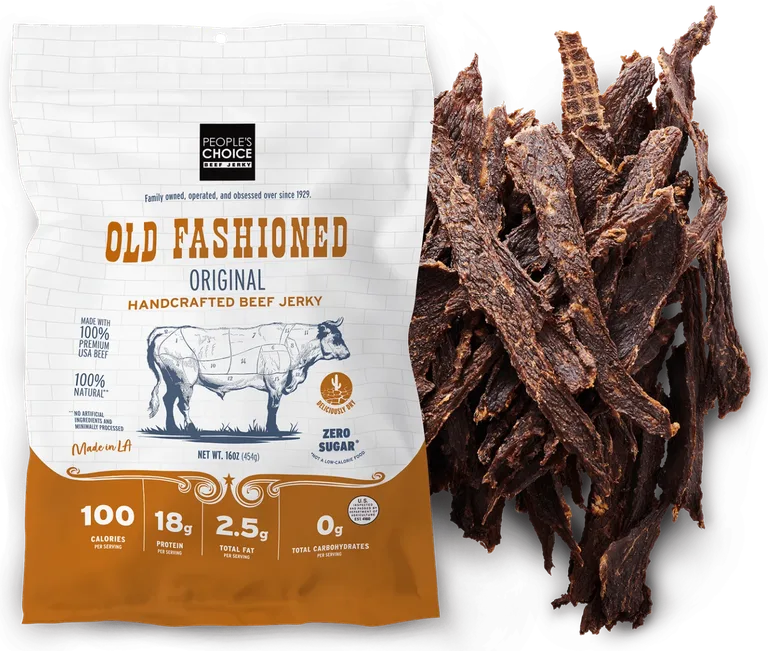
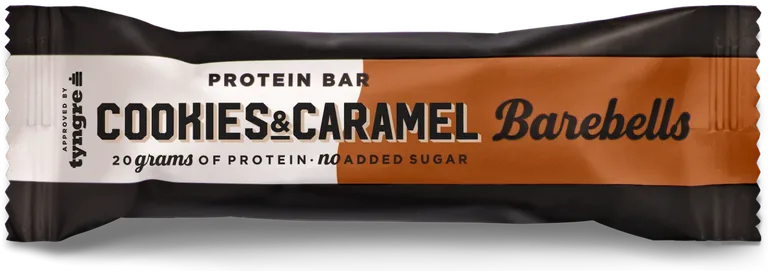
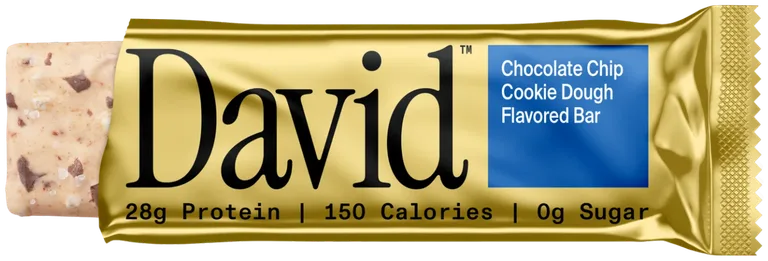
That is why we built finds box. It is 10 health-focused snacks and drinks from small brands you probably have not tried. Every item is high in protein, high in fiber, or low in sugar, and a real person on our team approved it. A David cookie dough bar with 28g of protein in 150 calories. A Poppi prebiotic soda. Top Seedz crackers made from seeds.
A curated box is $49.99 with shipping included, or you can build your own with up to 10 items. No subscription. Your receipt lists every item by name, so you can submit it to your LSA like any other expense. Most lifestyle accounts cover healthy food, but check your plan first.
Common questions
No. An HSA is pre-tax money for medical costs. An LSA is employer-funded, taxed as income, and covers whatever your employer allows.
Generally no. Snacks are not a medical expense, even healthy ones. An LSA or wellness stipend is the better fit, if your plan covers food.
Usually, yes. LSA money is typically treated as taxable income. Ask HR or a tax professional about your own situation.